

Instant Cash Advance: CashHoop
by Biskup Apps
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
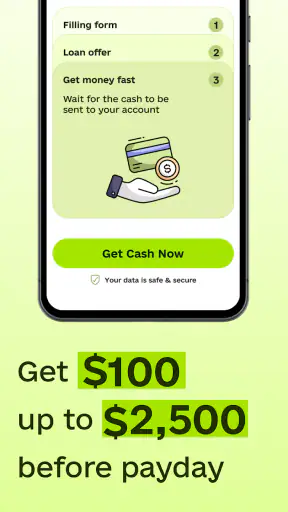
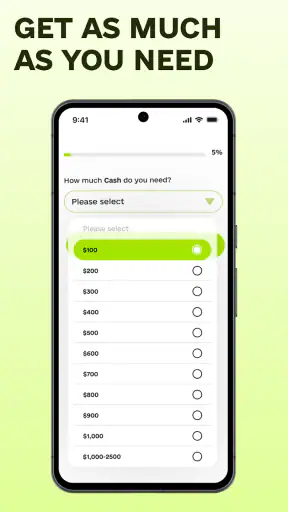
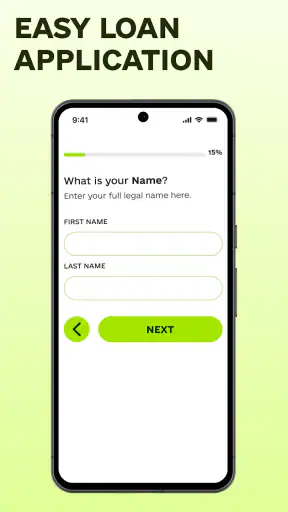
 Analysis by Getfullapps
Money apps are easy to judge by their promise and much harder to judge by the moment in which someone actually needs them. I looked at Instant Cash Advance: CashHoop as a finance app for those stressful gaps between an unexpected bill and the next dependable source of income. My main question was not simply whether it can request a cash advance, but whether the experience feels understandable when a user is tired, worried, working from a phone, or dealing with different reading, movement, or sensory needs.
CashHoop is made by Biskup Apps and is available free of charge. It sits in a category where speed matters, but so do explanations, careful decisions, and the ability to stop before accepting anything. The app also connects its cash-advance purpose with tax filing, which gives it a wider role than a single emergency-borrowing screen. That combination can be useful, although it also means users should pay attention to which task they are starting and what information each task requires.
The app has a 4.7 average from around 26 thousand ratings, with more than a million installs. That level of adoption makes it easier to understand why people are curious about it, but popularity is not a substitute for checking the terms shown during an individual application. A borrowing tool should be treated as a decision aid, not as spare income.
How CashHoop feels when clarity matters
I focus here on the part of CashHoop that matters most when money is tight: whether its cash-advance purpose helps a person make a clearer next move, rather than simply encouraging a quick tap. I also consider how keeping the tax-filing option in the same app may affect that decision. From there, the practical question is how to approach an advance without letting urgency crowd out a careful review.
Readability and navigation during a stressful request
My strongest impression is that a cash-advance app needs to reduce mental effort before it tries to reduce financial pressure. CashHoop’s purpose is immediately recognizable, which helps a first-time user decide whether it is relevant. The separate tax-filing angle is also potentially practical: someone opening the app for tax work does not have to use the same route as someone looking for help with an urgent expense.
That distinction matters more than it may seem. A person dealing with a late utility payment may open the app with one narrow goal and little patience for unrelated choices. I would approach the first screen slowly, identify whether I am entering the advance or tax workflow, and avoid tapping through simply because a button appears prominent. In finance, a clear next step is helpful only when the user understands what happens after it.
The app is suitable for Everyone, and it runs on Android devices using version 7.0 or later. Those details make it approachable for people who do not have a recent phone, including users who keep an older device because replacing it is expensive or inconvenient. Still, an older operating system does not automatically mean every person will find the interface comfortable. Screen size, display scaling, contrast, keyboard behavior, and the user’s own familiarity with financial forms can change the experience considerably.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I recommend reading every explanatory line rather than relying on the largest text or the most visually obvious control. A useful habit is to pause at each stage and ask three questions: what am I requesting, what information am I providing, and what commitment am I about to make? This is especially important when a cash advance feels urgent, because urgency can make a short screen seem more reassuring than it really is.
For people who prefer predictable navigation, the best workflow is to keep the process narrow. Finish one task before switching to another, keep personal documents nearby if tax filing is the goal, and use the phone’s normal text-size or display tools when reading becomes tiring. I would also avoid completing a financial application while walking, commuting, or sharing a screen with someone else. CashHoop may be convenient on a phone, but convenience should not turn into rushed consent.
Motor and sensory considerations
Accessibility is not limited to whether an app opens on an older device. It also includes how much precision a user needs, how much typing is involved, and whether important information can be understood without depending on one visual cue. CashHoop is most approachable for someone who can comfortably read mobile text, tap ordinary controls, and enter personal or financial information. Users with reduced dexterity may find any form-based finance process slower, particularly if fields require repeated corrections or if a small control must be selected accurately.
My practical advice is to use a stable surface, enable the phone’s preferred text and display settings before starting, and give yourself enough time to review each field. Voice input or an external keyboard may help with typing, but I would carefully proofread any automatically entered names, addresses, amounts, and dates. A transcription mistake in a financial form is more serious than a typo in a casual message.
For users with low vision, larger system text can improve reading, but it may also change how much content fits on a screen. That creates a trade-off: fewer words visible at once can mean more scrolling and a greater chance of missing surrounding context. I would scroll deliberately and look for the complete explanation around any action button rather than assuming the visible portion is the whole instruction.
People with color-vision differences should not make decisions based only on color, especially when distinguishing warnings, progress states, or confirmation messages. I would look for the accompanying wording and read the full message. Users with hearing loss should likewise favor written instructions and on-screen confirmations instead of relying on any sound or vibration. These are sensible habits for a finance app, although they cannot guarantee that every part of an individual phone setup will behave perfectly.
Cognitive load is another major consideration. A person with attention difficulties, dyslexia, anxiety, or a language-processing challenge may benefit from breaking the task into short sessions, taking screenshots for personal reference where appropriate, and having a trusted person read explanations aloud without sharing passwords or security codes. The important distinction is between getting help understanding a screen and handing control of a financial account to someone else.
Everyday situations where the app can help
Imagine a user notices that a necessary household bill is due before payday. They open CashHoop, review the advance pathway, and compare the displayed repayment information with the amount they actually need. The sensible use is to request only the smallest amount that solves the immediate problem, then record the repayment obligation in a calendar or budget. The app may make the request convenient, but the user still needs to decide whether the future deduction or repayment will create another shortfall.
That scenario shows why a cash advance is different from a budgeting app. A budgeting tool helps someone plan money already available or expected; CashHoop is aimed at accessing money sooner. A bank’s established overdraft facility, a credit card, or help from a trusted person may be a better option in some circumstances, depending on the terms and the user’s situation. I would compare the complete cost and timing before choosing, rather than assuming the fastest route is the cheapest.
The tax-filing side can suit someone who wants to handle tax work from the same phone rather than search for a separate service. The useful workflow is to gather the necessary records first, set aside uninterrupted time, and check entries before submitting anything. Combining tax preparation with an advance request may feel efficient, but I would keep those decisions mentally separate. A tax task can involve accuracy and deadlines; a borrowing decision involves future repayment pressure. Neither should be rushed because the other is open on the same screen.
CashHoop may also be useful for a user who has difficulty traveling to a physical office or who needs to work outside normal appointment hours. That is an important situational advantage of a mobile finance app. Someone with limited mobility, unpredictable work shifts, caregiving duties, or transportation barriers may value being able to begin from home. The benefit is practical rather than magical: the user still needs a private environment, a reliable connection, and enough concentration to review financial details.
Who should be cautious or choose another route
I would not recommend using a cash advance as a routine way to cover ordinary spending. If the same shortfall appears every pay cycle, the underlying issue is larger than an individual emergency, and borrowing earlier may simply move the pressure forward. A budget review, a conversation with a bill provider, a local assistance service, or advice from a qualified financial counselor may be more appropriate.
CashHoop is also not the right choice for someone who cannot comfortably understand the repayment obligation shown during the process. Asking a trusted person to explain general wording can help, but the final decision should remain with the account holder. If a user has difficulty reading the terms even after adjusting the phone, an in-person or human-assisted alternative may offer safer support.
Users who are highly concerned about entering sensitive information on a phone should take extra care with device security. I would use a personal device, avoid public Wi-Fi when possible, keep the operating system and screen lock current, and never share a verification code. These are not special features of CashHoop; they are basic precautions that become especially important when a finance app is involved.
Another trade-off is that a free download does not mean every financial outcome is free. The app costs nothing to install, but the user must examine the actual offer, repayment timing, and any applicable charges or conditions presented during the process. I would take a screenshot or write down the details for my own records before confirming, provided the screen contains no information that should be stored insecurely. If the terms are difficult to locate or understand, I would stop and seek clarification rather than proceed on assumption.
Small habits that make the experience safer and more inclusive
- Separate urgency from action: decide the exact bill or need first, then open the advance workflow, instead of browsing for an amount simply because it is available.
- Use accessibility settings before beginning: adjust text size, display scaling, and input preferences while still on the phone’s home screen so the form is easier to review.
- Read beyond the button: check nearby explanations, repayment language, and confirmation screens before tapping the next step.
- Keep support private: ask someone to help interpret instructions if needed, but do not disclose passwords, security codes, or unrestricted access to the device.
- Plan the return path: record the expected repayment date and compare it with rent, food, transport, and other fixed obligations before accepting an advance.
These habits reveal a broader strength and weakness. The strength is that a phone-based service can reduce travel and let users begin when their circumstances allow. The weakness is that a compact mobile interface may compress important financial context into a small space, and a user under pressure may not give it the attention it deserves. CashHoop can support access, but it cannot replace financial understanding or personal assistance.
What the current release means for potential users
The current version is 1.0.15, and the app was released on July 17, 2024. I mention this because people using older phones or relying on assistive settings should check that their device behaves properly before starting a time-sensitive task. The broad Android compatibility is helpful, but individual performance can still vary with hardware, screen configuration, and the way a person interacts with the phone.
As a finance app, CashHoop benefits from having a focused purpose rather than trying to become a full banking replacement. Its appeal is strongest for someone who needs to explore an advance or tax filing from a mobile device and is prepared to review the details carefully. It is less compelling for someone seeking long-term financial planning, debt counseling, comprehensive account management, or a human adviser who can explain every decision in conversation.
I also would not treat the high average rating as proof that the app will suit every ability or financial circumstance. Ratings often tell me that many users found the basic experience useful, but they do not answer the individual questions that matter most: Can I read it comfortably? Can I complete the form without assistance? Do I understand the repayment impact? Can I keep my information private while receiving help?
My inclusive verdict
After reviewing CashHoop through the lens of everyday access, I see a useful mobile option for people who need to investigate a cash advance or manage tax filing without going to an office. Its free availability, support for older Android devices, and clear finance focus make it approachable for a broad audience. The app is particularly well suited to users who can work independently on a phone, have a specific short-term need, and are willing to slow down for the financial details.
My recommendation comes with a firm condition: use CashHoop as a carefully reviewed financial tool, not as an automatic answer to a money problem. Read the complete offer, request only what is necessary, and make sure the repayment fits the rest of your budget. If reading, motor control, privacy, or comprehension makes the mobile process difficult, choose a service that provides stronger personal assistance rather than forcing yourself through it.
In the end, the app’s accessibility value comes from flexibility: it can be used from home, on a compatible older phone, and at a time that suits the user. Its main barrier is the same one found in many mobile finance services—the user must carry much of the responsibility for interpreting and accepting the consequences. For a careful, independent user with a genuine short-term need, CashHoop is worth considering. For recurring financial hardship or a need for guided support, a different option will likely be the wiser choice.
Pros
- Quick approval process for cash advances.
- User-friendly interface with intuitive design.
- No credit check required for application.
- Flexible repayment options available.
- Fast deposit directly to your bank account.
Cons
- High interest rates compared to traditional loans.
- Limited availability in some regions.
- Strict eligibility criteria for new users.
- Limited customer support hours.
- Requires access to personal financial data.
FAQs for Instant Cash Advance: CashHoop
What is Instant Cash Advance: CashHoop and how does it work?
Instant Cash Advance: CashHoop is a financial app designed to provide users with quick, small cash advances to help manage unexpected expenses. After downloading the app, users can apply for a cash advance by linking their bank account. The app evaluates your financial history to approve an advance, which is then deposited directly into your account.
Is Instant Cash Advance: CashHoop safe to use?
Yes, CashHoop employs industry-standard encryption and security measures to protect your personal and financial information. It requires users to link their bank account using secure, encrypted connections. It's important to review the app’s privacy policy and terms of service to understand how your data is handled.
What are the eligibility requirements for using CashHoop?
To qualify for a cash advance through CashHoop, you must be at least 18 years old, have a valid bank account, and demonstrate a regular income. The app may require additional information to verify your identity and financial situation, ensuring you meet their lending criteria.
Are there any fees associated with using CashHoop?
CashHoop may charge fees for their cash advance services, which can vary depending on the amount borrowed and repayment terms. It’s crucial to read the fee structure carefully before accepting any advance. Some users may find the fees comparable to traditional payday loans, so consider your options.
How quickly can I receive funds from CashHoop?
Once your application is approved, funds from CashHoop are typically deposited into your bank account within one to two business days. The exact timing can depend on your bank’s processing times. For urgent needs, it’s advisable to apply as early as possible to avoid delays.











